Recent Post
NRI Guide to Buying Property in Kolkata
NRIs can buy residential and commercial property in India without any permission from the RBI. The only major restriction is on agricultural land, plantation property and farmhouses. Yet rules around payment routes, TDS, taxes and paperwork still hold many overseas Indians back from buying a home in Kolkata.
If you live in Dubai, London, Singapore, Toronto or New Jersey, you have probably asked these questions yourself. Can NRI buy property in India without coming home? Which account should the money come from? Who handles TDS? What happens at registration if you are 8,000 km away?
Here is the good news. Buying a home in India as an NRI is far simpler than most people think. You need the right documents, the right payment route and a developer who knows the NRI process inside out. This guide walks you through every step, in plain language, so you can move from “someday” to “keys in hand.”
Why Kolkata Deserves a Place in Your Portfolio
Before the rules, a quick look at why so many NRIs are choosing Kolkata over other metros.
- Value for money. Premium apartments in Kolkata still cost noticeably less than comparable homes in Mumbai, Bengaluru or Delhi NCR, so your foreign earnings stretch further.
- Infrastructure that keeps growing. Metro extensions, the New Town and Sector V business belt, and planned links like the proposed EM Bypass to New Town flyover are reshaping how the city moves.
- A home for every life stage. A rental asset today, a base for ageing parents tomorrow, and a retirement home when you return for good.
- Emotional return on investment. Some investments are measured in yield. Others are measured in Durga Pujas spent at home.
Whether you are looking at NRI flats in Kolkata for rental income or a forever home, the legal framework is the same. Let us break it down.
Also Read: Essential Tips for NRIs Investing in Indian Real Estate
Can NRI Buy Property in India? The Short Answer
Yes. Under the Foreign Exchange Management Act (FEMA), NRIs and Overseas Citizens of India (OCIs) can buy residential and commercial property in India under general permission. You do not need prior approval from the Reserve Bank of India (RBI), and there is no limit on the number of residential or commercial properties you can own.
What you cannot buy is:
- Agricultural land
- Plantation property
- Farmhouses
These can only come to an NRI through inheritance or with specific approvals. So a 3 BHK apartment, a luxury villa or an office space in Kolkata is completely within reach.
RBI Guidelines for NRI Buying Property in India
The RBI guidelines for NRI buying property in India focus on one thing: how the money moves. Get this right, and the rest of the process is smooth.
1. Payment must be in Indian Rupees through banking channels
You cannot pay a developer in foreign currency, cash or traveller’s cheques.
Payment must be made in rupees through:
- Inward remittance from abroad through normal banking channels, or
- Funds held in your NRE, NRO or FCNR(B) account in India
2. Your payment route decides your repatriation rights later
This is the part most buyers overlook.
| Payment source | What it means when you sell |
|---|---|
| Inward remittance / NRE / FCNR(B) | Sale proceeds can be repatriated abroad, up to the amount you originally brought in |
| NRO account (rupee income earned in India) | Proceeds go to your NRO account and follow NRO repatriation limits |
3. Renting out is allowed
You can lease your Kolkata flat freely. Rental income, after applicable taxes, can be credited to your NRO account and remitted abroad within permitted limits.
Rules for NRI Buying Property in India: A Quick Checklist
Here are the core rules for NRI buying property in India in one place:
- You must hold a PAN (Permanent Account Number). It is mandatory for registration, TDS and tax filing.
- Open an NRE or NRO account with an Indian bank before you start paying.
- Buy only RERA-registered projects so your money, timeline and specifications are legally protected.
- Pay only through banking channels and keep every receipt.
- If you cannot be present, appoint a specific power of attorney (more on this below).
- Pay stamp duty and registration fees as per West Bengal rules at the time of registration.
Documents Required for NRI to Buy Property in India
Keep this list handy. The documents required for NRI to buy property in India fall into three groups.
Your identity and residency papers
- Valid Indian passport (or foreign passport plus OCI card)
- Visa, work permit or residence permit
- PAN card
- Overseas address proof (utility bill, bank statement or tenancy document)
- Indian address proof, if any
- Recent passport-size photographs
Banking and financial papers
- NRE / NRO / FCNR(B) account statements
- Proof of inward remittance (FIRC or bank advice)
- For a home loan: salary slips, employment contract, overseas tax returns, bank statements and credit report
Property papers to collect and keep safe
- Allotment letter and agreement for sale
- RERA registration details of the project
- Title documents and sanctioned building plan
- Payment receipts from the developer
- TDS deposit challan and certificate
- Registered sale deed, plus completion or occupancy certificate at possession
- Power of attorney deed, if used.
NRI Buying Property in India TDS: Who Deducts What?
TDS confuses almost every NRI buyer, so let us make it simple. There are two very different situations.
When you (the NRI) buy from a developer or a resident seller
You are the buyer, so you deduct the TDS.
- If the property value is ₹50 lakh or more, deduct 1% TDS on the total amount you pay to the seller.
- Deposit it online using your PAN through the prescribed challan-cum-statement (Form 141 under the new Income-tax Act, 2025, which replaced Form 26QB from April 2026).
- No TAN is needed for this.
- Download the TDS certificate and share it with the seller.
If you are buying an under-construction home, TDS is deducted on every instalment as you pay it, not just at the end.
Tax Implications for NRI Buying Property in India
- At purchase: Budget roughly 6% to 7% stamp duty in Kolkata (based on value and location) plus about 1% registration fee; confirm current rates on the West Bengal registration portal. GST applies only to under-construction homes, and 1% TDS applies if the value is ₹50 lakh or more.
- While you own it: Rental income is taxable in India, with a 30% standard deduction and home loan interest deduction (subject to limits). Your tenant must deduct TDS on rent paid to an NRI, and you can file an Indian return to claim back any excess.
- When you sell: Long-term gains (held over 24 months) are taxed at 12.5% without indexation; short-term gains at your slab rate. Reinvesting in another residential property in India can earn exemptions, subject to conditions.
Double taxation
India has Double Taxation Avoidance Agreements (DTAA) with most countries where NRIs live, including the US, UK, UAE, Singapore and Canada. You can usually claim credit abroad for tax paid in India. Speak to a chartered accountant who handles NRI cases in both countries.
How to Choose the Right NRI Apartment in Kolkata
Rules and paperwork matter, but the home matters most. When you compare an NRI apartment in Kolkata, look at:
- Developer track record: How many projects have they actually handed over?
- RERA registration and transparent pricing: No hidden charges at possession.
- Location for your goal: Rental demand near IT hubs, or a quieter green neighbourhood for parents.
- Low-maintenance living: Gated security, power backup and a well-run association make managing from abroad easier.
- After-sales support: Who will help you with handover, interiors or leasing when you are not here?
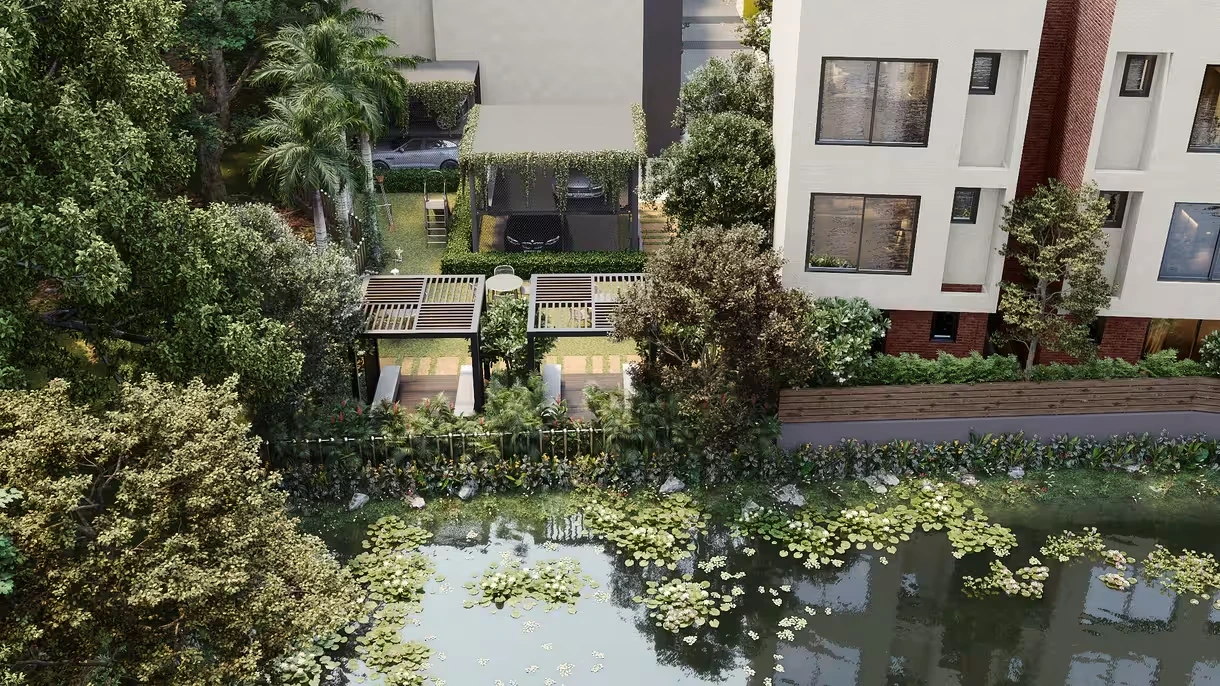
Sugam Homes has options across these needs. Families looking for a premium South Kolkata address explore luxury 3 and 4 BHK homes off New Alipore, right behind the Tollygunge Club. Buyers who want to be close to the Sector V business belt look for homes beside the East Kolkata Wetlands. You can also browse more 3 BHK flats in Kolkata in one place.
Check out our blog on: Villa or Apartment, What You Should Choose: A Guide for NRIs (Investment & Lifestyle)
Coming Home, With People Who Know the Way
Buying property from across the world is a big decision. You are trusting someone with your savings, your timelines and, often, your parents’ future comfort. That trust should be earned, not assumed.
For more than 35 years, Sugam Homes has been building homes across Kolkata, from Garia, Narendrapur and New Alipore to Baguihati, Jessore Road and Konnagar. Thousands of families, including many who live abroad, have collected keys to homes we have handed over. That experience shows up in the small things: knowing which documents a bank will ask for, how a POA should be worded, and how to keep an overseas buyer updated without them having to chase.
We also believe in being upfront. Every ongoing Sugam Homes project is RERA registered, pricing is shared clearly, and our team will always tell you when a question is better answered by your chartered accountant or lawyer. Tax and FEMA rules do change, so we encourage every NRI buyer to verify the latest position before signing.
If you are ready to explore your next home back home, start with our NRI Space or send us an enquiry. We will walk you through the process at your pace, from whichever time zone you are in.
Frequently Asked Questions
1. Can NRI buy property in India?
Yes. Under RBI guidelines, NRIs and OCIs can buy residential and commercial property in India without prior permission. Only agricultural land, plantation property and farmhouses are restricted.
2. What are the TDS rules for NRI buying property in India?
If the property value is ₹50 lakh or more, the NRI buyer deducts 1% TDS on the amount paid to the developer or resident seller and deposits it using their PAN. No TAN is required.
3. Can NRI buy property in India without visiting?
Yes. You can shortlist through virtual tours, pay through your NRE, NRO or FCNR(B) account and appoint a trusted person through a specific power of attorney to sign and register on your behalf.
4. Can NRI buy property in India on loan?
Yes. Indian banks and housing finance companies offer NRI home loans of up to 75% to 90% of the property value, depending on the price band. EMIs are paid from NRE, NRO, or FCNR(B) accounts or through inward remittance.

- Sugamhomes Blogshttps://www.sugamhomes.com/blog/author/sugamhomes_blog/